
Executive Summary
West Africa’s commercial and hospitality built environment is in the middle of the most consequential expansion cycle of this generation. Nigeria leads Africa’s hotel construction pipeline with 14,392 rooms in active development. Nigeria’s real estate sector has been confirmed as the third-largest contributor to national GDP following the NBS rebasing exercise, accounting for 13.36% of economic output. Africa’s overall hotel pipeline has reached a record 123,846 rooms across 675 hotels, growing 18.6% year-on-year. International tourist arrivals to Africa grew 8% in 2025, the strongest growth rate of any global region.
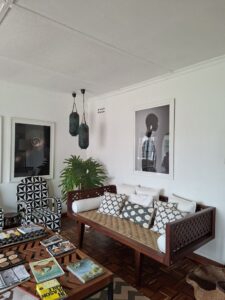
This report provides MOD-ii’s annual assessment of the interior design market across West Africa’s four largest commercial and hospitality real estate markets (Nigeria, Ghana, Côte d’Ivoire and Senegal), drawing on data from across the sector and our own project delivery experience across 78 completed schemes in six African countries.
It is the most comprehensive published assessment of West Africa’s interior design market produced by any practice operating in the region.
Part One: Nigeria, The Market Leading the Continent
Real Estate and Commercial Market
Nigeria’s real estate sector entered 2026 in a structurally stronger position than the raw economic statistics of the preceding three years might suggest. The NBS rebasing exercise, using 2019 as the new base year, confirmed real estate as the third-largest contributor to Nigerian GDP at 13.36% of economic output, a recalibration that reflects the sector’s genuine weight in the economy rather than the undercount produced by an outdated baseline.
Real GDP grew 3.98% year-on-year in the third quarter of 2025, with non-oil sector growth providing the majority of momentum. The naira stabilised at approximately ₦1,363 to ₦1,400 to the US dollar from January 2026, following a period of dramatic devaluation that had significantly compressed client confidence in medium-term commercial investment. The Central Bank cut its Monetary Policy Rate by 50 basis points to 26.5% in February 2026, signalling institutional confidence that inflation, which fell for ten consecutive months to reach 15.1% in January, is on a sustainable downward path.
Lagos accounts for 69% of Nigeria’s total managed office supply, according to the Nigeria Managed Office Report 2026 published by Fortren & Company. Demand within that supply is being driven primarily by small and medium-sized enterprises across fintech, information technology, finance, real estate, and the non-profit sector. Knight Frank Nigeria’s March 2026 market report identifies decentralisation, businesses relocating from Victoria Island and Ikoyi to secondary districts to reduce costs and commute times, as the defining structural trend of the year. Secondary business district vacancy is tightening modestly. Prime Grade A rents on Victoria Island hold at approximately ₦95,000 to ₦120,000 per square metre per year in a tenant-led market where landlords are adopting flexible lease structures to compete for quality occupiers.
The Nigeria Tax Act 2025, effective from January 2026, is formalising property transactions across the country in ways that are gradually improving the quality and reliability of commercial lease documentation, a structural improvement for a market that has historically operated with lower transaction transparency than its development ambitions require.
Construction Cost Environment
Nigeria’s construction cost environment in 2026 is among the most challenging of any major market globally. An independent cost analysis found that total construction cost for a standard four-bedroom house rose from ₦135.36 million in January 2025 to ₦163.81 million by April 2026, an increase of approximately 21% in fifteen months. Cement prices reached ₦11,500 to ₦15,000 per 50-kilogram bag in several Nigerian regions by March 2026, up from approximately ₦7,500 in the final quarter of 2025. Lagos was identified as likely to record one of the highest construction cost growth rates of any major global city in 2025.
Roughly 80% of Nigeria’s non-cement construction inputs are imported. With the naira’s weakened position adding significant cost exposure to all imported materials, and import duties adding a further 20 to 35% on premium finishes, the financial case for local material specification has become as compelling as the design and sustainability arguments.
The Nigerian Society of Engineers and the Nigerian Institute of Building project that the construction sector will require approximately 499,000 workers in 2026, up from 439,000 the year before, with an acute shortage of skilled artisans and experienced professionals due to long-term underinvestment in trades and the continuing migration of qualified practitioners overseas. Both bodies have specifically endorsed Building Information Modelling and AI-assisted project management as the sector’s shift toward what they describe as “intelligent resilience.”
Construction industry CAGR is forecast at 3.1% for the period 2026 to 2029, according to Research and Markets, modest but positive growth underpinned by energy sector investment, infrastructure development, and the sustained private sector activity described throughout this report.
Hospitality Market
Nigeria’s position in Africa’s hospitality market in 2026 is without precedent. The Hotel Chain Development Pipelines in Africa 2026 report from the W Hospitality Group places Nigeria first in Africa with 14,392 rooms in active development, ahead of South Africa at 10,870, Kenya at 8,653, Egypt at 6,530, and Morocco at 5,960.
The country’s hospitality sector is projected to contribute approximately 4.5% of national GDP in 2026, according to W Hospitality Group’s Managing Director Trevor Ward, speaking to CNBC Africa in February. Hotel occupancy across Nigeria is forecast to hold stable at approximately 70%, with revenue per available room continuing to increase through higher pricing rather than volume alone, reflecting growing pricing power in a market where quality supply remains constrained relative to demand.
Landmark projects include the major extension of Eko Hotels and Suites in Lagos and the expansion of the Transcorp Hilton in Abuja, two of the most significant hospitality investments in Nigerian history, both active in 2026.
Africa registered an 8% increase in international tourist arrivals in 2025, the strongest growth rate of any global region according to UN Tourism, providing a structural demand tailwind for Nigeria’s hospitality expansion. The wider African hotel pipeline reached a record 123,846 rooms across 675 hotels, with West Africa accounting for 14 of the continent’s 18 active hotel development markets.
Interior Design Implications for Nigeria
The convergence of factors described above, a stabilising macro environment, a record hospitality construction pipeline, a formalising commercial property market, and a construction cost environment that rewards design intelligence over specification complacency, creates a set of interior design conditions that MOD-ii believes are without parallel in West Africa’s recent history.
The businesses and developers who respond to these conditions with genuinely ambitious, evidence-based, culturally grounded design will establish the benchmark for Nigerian commercial and hospitality space for the next decade. Those who respond with generic, import-dependent specification are exposed to cost volatility, talent competition, and the growing sophistication of a Nigerian client and occupier base that is increasingly capable of identifying and demanding better.
Part Two: Ghana, West Africa’s Second-Largest Market
Ghana’s commercial and hospitality market in 2026 presents a picture of measured recovery and genuine pipeline growth, against the backdrop of an economy navigating its way through a debt restructuring programme that has constrained public spending but left the private sector more resilient than many observers expected.

The W Hospitality Group’s 2026 pipeline report identifies Ghana with 26 hotels and 3,942 rooms in active development, a meaningful programme that reflects international brand confidence in Ghana’s medium-term hospitality prospects. Among the landmark projects active in 2026 is the Rock City Hotel development, identified by the W Hospitality Group as a significant new addition to Ghana’s hospitality stock.
Grade A office vacancy in Accra sits at approximately 14.2%, higher than Lagos’s equivalent figure, reflecting a market that has seen meaningful new supply delivered against demand that has been more constrained by economic conditions than Nigeria’s. This higher vacancy rate creates a tenant’s market in Accra that offers opportunities for occupiers willing to commit to quality space on terms that would not have been available two or three years ago.
Ghana’s construction sector is growing, with the World Bank reporting 7.8% construction growth, a figure that reflects infrastructure investment and the private sector activity that is gradually rebuilding momentum as the debt restructuring programme creates greater fiscal space.
Interior design implications for Ghana: The combination of higher office vacancy and a growing hospitality pipeline creates a refurbishment and repositioning opportunity, with landlords holding vacant Grade A space upgrading interior quality to compete for occupiers, and hotel developers raising specification standards to meet international brand requirements in a market where the competitive landscape is intensifying.
Part Three: Côte d’Ivoire, The Francophone Growth Leader
Côte d’Ivoire’s construction sector grew at approximately 7.8% in the most recent reporting period, making it one of the fastest-growing construction markets in West Africa. Abidjan’s commercial real estate market is benefiting from the country’s sustained economic momentum. Côte d’Ivoire has been one of the most consistently high-growth economies in sub-Saharan Africa over the past decade, and the built environment is beginning to reflect the confidence that sustained growth creates.
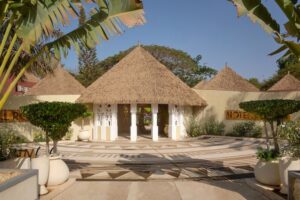
The hospitality market is developing rapidly, with international hotel brands establishing or expanding their Abidjan presence in anticipation of continued business travel and tourism growth. Côte d’Ivoire’s position as the gateway to Francophone West Africa, a region of several hundred million people with significant and growing purchasing power, gives its commercial real estate market a depth of demand catchment that smaller West African markets cannot match.
Interior design implications for Côte d’Ivoire: The growth market creates an appetite for premium design that the local supply of qualified interior design practice has not fully kept pace with, an opportunity for practices with international-standard delivery capability and genuine pan-African experience.
Part Four: Senegal, The DAKAR Gateway
Senegal’s interior design and hospitality market in 2026 is shaped primarily by Dakar’s growing role as a regional business hub and its position as one of Africa’s more politically stable major capitals, a characteristic that attracts both international business operations and the NGO and diplomatic activity that generates consistent demand for quality commercial and hospitality space.
The recently opened Blaise Diagne International Airport, combined with Dakar’s position on direct transatlantic flight routes, has reinforced the city’s gateway status and driven hotel development that is visibly improving in specification standard relative to five years ago. Senegal’s hospitality pipeline is smaller in absolute terms than Nigeria’s or Ghana’s, but it reflects genuine quality ambition rather than simply volume growth.
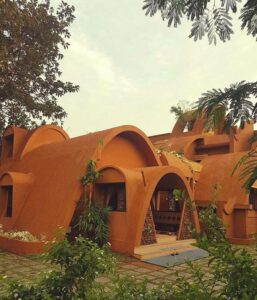
Interior design implications for Senegal: Dakar presents a market for internationally experienced design practices with the cultural sensitivity to operate effectively in a predominantly Francophone, West African Islamic context, a brief that demands a different set of cultural and spatial sensitivities than MOD-ii’s Nigerian home market, but one that shares the same fundamental commitment to design that is excellent and authentically African simultaneously.
Cross-Market Intelligence: What West Africa’s Design Market Tells Us in 2026
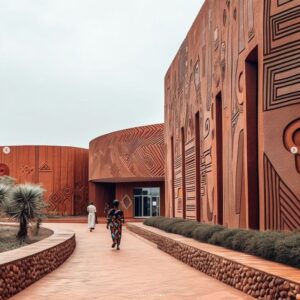
Reading across the four markets profiled in this report, several consistent themes emerge that are reshaping interior design practice across the region.
Hospitality is the demand driver. With West Africa accounting for 14 of Africa’s 18 active hotel development markets and Nigeria alone leading the continent with 14,392 rooms in development, hospitality design is the highest-growth category across the region. The international brands and private developers driving this pipeline are raising specification expectations that ripple through the broader commercial market.
Local materials intelligence is becoming a competitive advantage. Across all four markets, the combination of currency exposure on imported materials and growing cultural confidence in locally-sourced alternatives is shifting the specification conversation. The design practices that have built genuine local material knowledge, tested, documented, and supply-chain-backed, are better positioned to serve clients navigating 2026’s cost environment than those still defaulting to imported specifications.
The talent shortage is a regional, not just Nigerian, challenge. Nigeria’s 499,000 construction worker shortfall is the most documented, but equivalent pressures exist in Ghana, Côte d’Ivoire and Senegal. This creates a premium for practices with established, qualified teams, and a risk for clients who assume that a practice with a polished marketing presence necessarily has the professional depth to deliver on it.
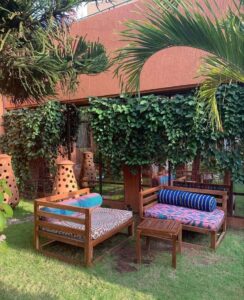
Cultural authenticity is increasingly the design differentiator that international brands are seeking. Showcase Africa’s 2026 hospitality investment analysis names “cultural storytelling and personalisation” as the defining boutique investment thesis. This is not a local market trend, it is a global convergence on the insight that the most commercially compelling hospitality and commercial environments are those that could only exist in their specific place.
Brief Us on Your West Africa Project
Whether your project sits in Lagos, Accra, Abidjan, Dakar, or elsewhere across the region, MOD-ii’s pan-African practice brings the market intelligence, local procurement capability, and design rigour that West Africa’s 2026 commercial and hospitality opportunity demands.
Contact our team to discuss your project.
